Pricing Models, Vega and Implied Volatility
About This Webcast
This webinar reviews implied volatility and its potential impact on option pricing. During this webinar, OIC instructor Roma Colwell will lead an overview of volatility for investors who want to better understand this important options topic. Among the main discussion points are: Variables of the Black-Scholes formula The impact of Implied Volatility amongst different options Vega as a metric, and how it relates to Implied Volatility changes
Speakers
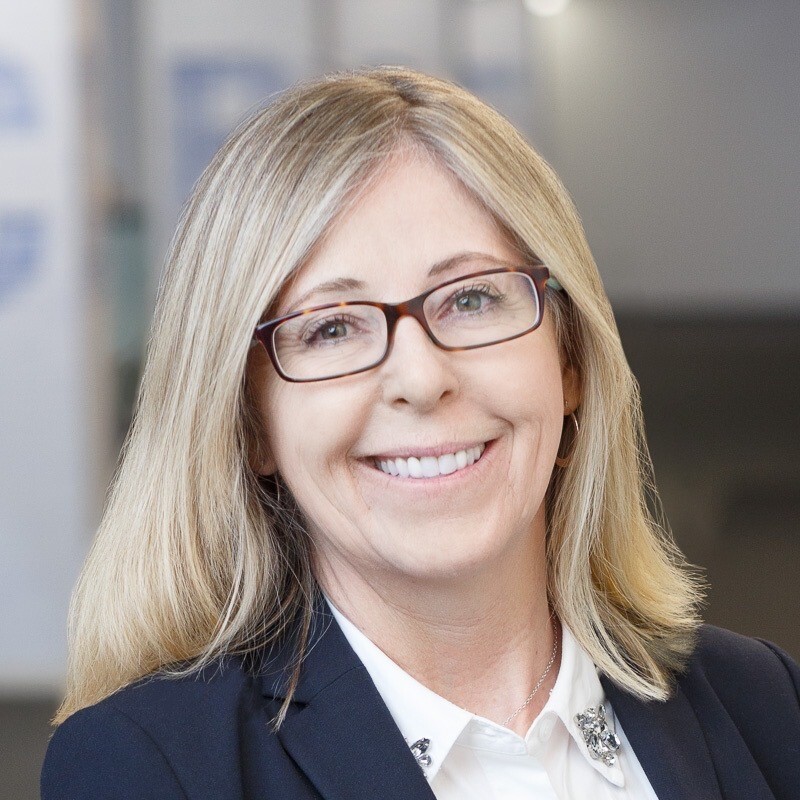
Roma Colwell
Associate Principal, Investor Education , OCC (The Options Clearing Corporation)
Roma Colwell is an Associate Principal, Investor Education at OCC and is a certified instructor for The Options Industry Council (OIC). Roma has more than 27 years in the securities industry, 18 of which were spent as a floor broker, market maker, specialist and risk manager in both San Francisco and Chicago. Prior to joining OIC, Roma was an instructor at the Options Institute, the education branch of Cboe Global Markets, formerly the Chicago Board Options Exchange, where she conducted option seminars for domestic and international segments of the investing community.